Market Insight
Fallowfield HMO or Family Home? How Your Property Type Changes Its Value
Investors and families assess Fallowfield properties differently. Rental yield, licensing, layout and gardens all shape value — and how you should market your home.
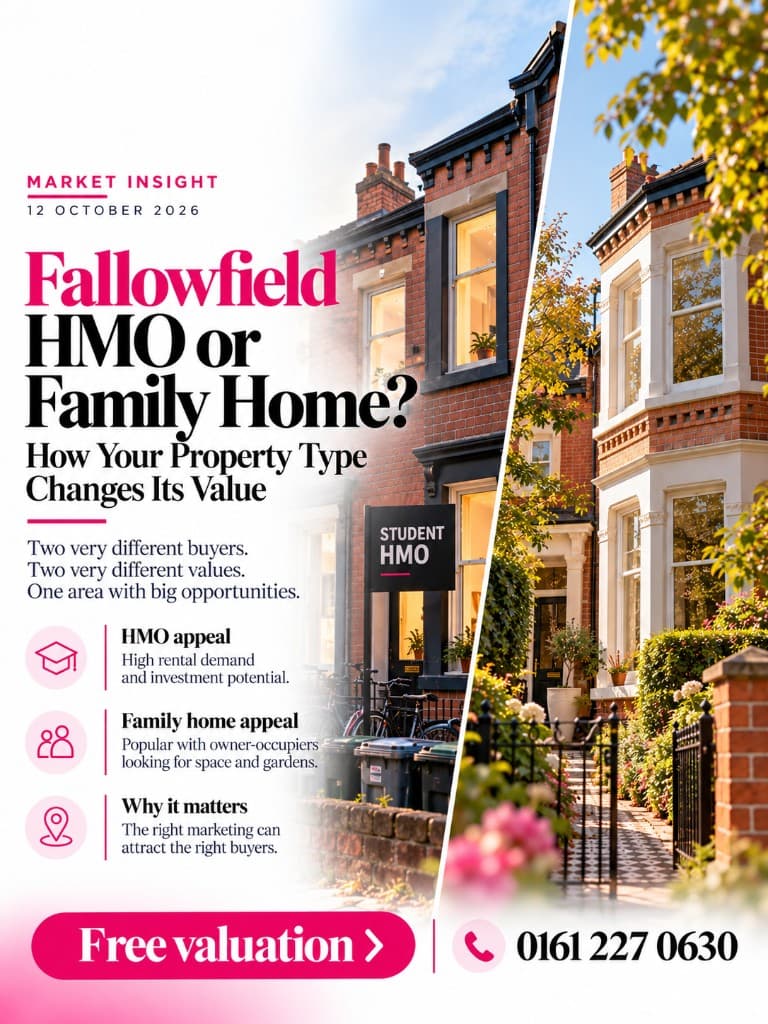
If you are thinking about selling a property in Fallowfield, Manchester, one of the most important questions to consider is who your potential buyers might be.
An established house in multiple occupation (HMO) could appeal to investors looking for rental income, while a similar property might attract families searching for a long-term home.
These two audiences often assess properties very differently.
For landlords and homeowners in Fallowfield, understanding those differences can help shape a more effective selling strategy.
Why Fallowfield has two distinct property markets
Fallowfield is a well-established South Manchester neighbourhood known for its student population, traditional residential streets and proximity to Manchester's universities.
The area contains a mixture of Victorian terraces, semi-detached homes, shared rental properties and purpose-built accommodation.
This creates a market in which both property investors and owner-occupiers may be interested in similar buildings for very different reasons.
However, property values are influenced by much more than location alone.
Condition, size, layout, rental income, licensing, planning status and the availability of comparable properties can all affect what a buyer is prepared to pay.
1. How investors value HMO properties in Fallowfield
An HMO is generally a property occupied by at least three people forming more than one household who share facilities such as a kitchen or bathroom.
For an investor considering buying an HMO in Fallowfield, the financial performance of the property may be a major consideration.
Rental income and yield
Investors commonly assess the rent a property generates alongside its purchase price.
For example, consider a hypothetical five-bedroom HMO generating £600 per room per month.
This would produce:
- Monthly gross rental income: £3,000
- Annual gross rental income: £36,000
If the property were purchased for £400,000, the gross rental yield would be 9%.
These figures are illustrative rather than verified local market averages.
Importantly, gross rental yield does not represent the investor's actual profit.
Maintenance, management fees, insurance, utilities, void periods, licensing, finance and taxation can all affect the investment's performance.
Licensing and compliance
Buyers considering an HMO will also want to understand its legal and regulatory position.
Relevant considerations may include HMO licensing, planning permission, applicable Article 4 restrictions, fire safety standards and tenancy arrangements.
A property with clear documentation and an established lawful use may be easier for prospective investors to assess.
Sellers should avoid assuming that an existing HMO licence automatically establishes planning permission or that permissions will necessarily transfer to a new owner.
Existing tenants
An HMO sold with tenants in place may appeal to an investor looking for an established rental operation.
However, tenancy agreements, deposits, payment records and legal obligations need careful consideration.
Having the relevant documentation available can help prospective buyers understand what they are purchasing.
2. How families value property in Fallowfield
For a family buying a home in Fallowfield, the decision may be based on a completely different set of priorities.
Instead of focusing on rental yield, owner-occupiers often consider whether the property suits their lifestyle.
Living space and layout
A family may value a separate living room, practical kitchen, comfortable bedrooms and useful storage.
Properties previously arranged for shared accommodation may have layouts that differ from those preferred by owner-occupiers.
For example, a reception room currently used as a bedroom might be more appealing as a family living space.
However, sellers should assess costs and any necessary permissions before undertaking major alterations.
Gardens and outdoor areas
Private outdoor space can be an attractive feature for families.
A well-presented garden, tidy patio and usable seating area can help buyers imagine living in the property.
Expensive landscaping is not always necessary. Simple maintenance and thoughtful presentation can improve first impressions.
Property condition
Buyers looking for a family home may pay close attention to kitchens, bathrooms, decoration, energy efficiency and the likelihood of future repair costs.
Some buyers prefer a move-in-ready property, while others are comfortable undertaking improvements.
Understanding the likely audience can help sellers decide which preparation work is worthwhile.
3. Is an HMO worth more than a family home?
There is no universal answer.
An established HMO may appeal to investors because of its rental income, occupancy arrangements and investment potential.
However, a property with a spacious layout, attractive garden and good overall condition may also attract strong interest from owner-occupiers.
The market value depends on the individual property and the available evidence.
Important factors include:
- Recent comparable property sales
- Size and condition
- Current rental income and operating costs
- Licensing and planning status
- Property layout and flexibility
- Garden and parking arrangements
- Exact location
- Demand from different buyer groups
A professional valuation should consider the property's characteristics rather than assuming one type of use will always achieve a higher price.
4. Why marketing an HMO is different from marketing a family home
Different buyers need different information.
Marketing to property investors
An investor-focused listing may benefit from:
- Accurate rental income information
- Current tenancy details
- Floor plans and room dimensions
- Licensing and planning documentation
- Relevant operating costs
- Professional property photography
Investors need sufficient information to evaluate the property realistically.
Marketing to families
A family-focused listing may place greater emphasis on:
- Living space and room proportions
- Gardens and outdoor areas
- Kitchens and bathrooms
- Natural light
- Storage and practical layout
- Nearby transport and amenities
High-quality photography and an accurate property description can help buyers understand the home's potential.
Could you target both markets?
Some Fallowfield properties may attract both investors and owner-occupiers.
However, sellers should establish the property's legal use, tenancy position and any relevant planning requirements before suggesting alternative uses.
A property cannot automatically be marketed as suitable for every use without considering the applicable restrictions.
5. Common mistakes when selling property in Fallowfield
Using an online valuation as the only guide
Online estimates can provide a useful starting point, but they may not account for individual property features, tenancy arrangements, licensing or condition.
Assuming more bedrooms always means more value
Additional bedrooms can increase rental capacity or accommodation, but layout, room sizes and legal requirements also matter.
Marketing only to investors
Some landlords may overlook owner-occupier interest in their property.
Depending on its characteristics and legal position, a property might appeal to more than one buyer group.
Overlooking important documents
Incomplete tenancy records, unclear permissions or missing compliance information can create uncertainty during the sale.
Preparing documentation early may help avoid delays.
6. Preparing your Fallowfield property for sale
Before placing your property on the market, consider taking several practical steps.
Understand its current use. Establish whether the property is occupied as a single household home, a shared rental property or an HMO.
Review your documentation. Gather relevant tenancy agreements, licences, planning documents and safety records.
Identify potential buyers. Consider whether investors, families or both are likely to be interested.
Prepare the property. Address minor maintenance issues, declutter and arrange professional photography.
Review comparable sales. Consider recently sold properties with genuinely similar characteristics.
Obtain a property-specific valuation. Seek an assessment that accounts for the individual features and circumstances of your property.
7. Why choosing the right Manchester estate agent matters
Selling a property in Fallowfield requires an understanding of the local market and the expectations of different buyers.
An investor may need detailed financial and compliance information.
A family may want to understand how the home could suit their daily life.
Recognising these differences can help establish an appropriate asking price, create more effective marketing and reach suitable buyers.
At Delisa Miller (NW) Ltd, we help homeowners and landlords across Manchester consider their selling options and develop a marketing strategy appropriate to their property.
Thinking of selling your Fallowfield property?
Whether you own a Victorian terrace, a student rental property, an established HMO or a family home, understanding your property's position in the market is an important first step.
We offer free, no-obligation property valuations for homeowners considering selling in Manchester.
Our team can discuss your property's features, potential buyer audience and marketing options.
Book your free property valuation at delisamiller.co.uk/selling/valuation or call 0161 227 0630.
Delisa Miller (NW) Ltd — 44 Hulme High Street, Manchester, M15 5JP.
This article is for general information. HMO licensing, planning requirements and tenancy obligations should be checked against current legislation and official local authority guidance before making property decisions.
Related reading
Got a Property Question?
Our team is here to help. Whether you're buying, selling or letting — get in touch today.