Valuation Guide
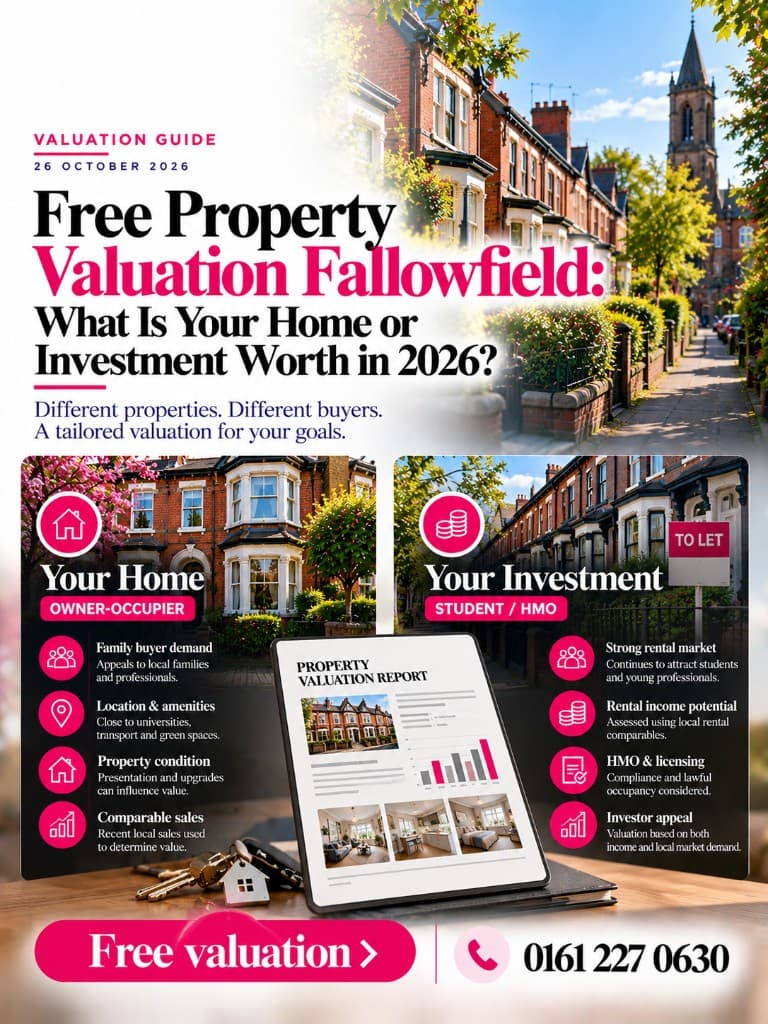
Free Property Valuation Fallowfield: What Is Your Home or Investment Worth in 2026?
Family terraces and student investments are valued differently. How Fallowfield sellers and landlords should prepare for a free valuation in 2026.
If you own a property in Fallowfield, Manchester, you may be wondering how much it could be worth in 2026.
Perhaps you live in a traditional terraced house and are considering moving. Maybe you own a student rental property, an established HMO or another residential investment.
Although these properties may look similar from the street, their valuations can involve different considerations.
A family home is typically assessed with reference to comparable residential sales and the needs of potential owner-occupiers.
An investment property may also require an assessment of rental income, tenancy arrangements, operating costs and its appeal to investors.
However, rental income alone does not determine a property's market value.
In this guide, Delisa Miller (NW) Ltd explains how property valuations work in Fallowfield, what can influence your home's selling price and why investment properties require careful analysis.
1. Why Fallowfield properties need individual valuations
Fallowfield is an established residential area in South Manchester, containing traditional terraces, semi-detached houses, apartments and shared rental accommodation.
Its proximity to Manchester's universities is one factor that may influence interest in certain rental properties.
However, the local market is not uniform.
A three-bedroom family home, a four-bedroom student rental and a licensed HMO may have different characteristics and attract different buyers.
What should a valuation consider?
A professional assessment should examine:
- Exact street location
- Property type
- Internal floor area
- Bedroom count and layout
- Condition
- Garden and parking
- Tenure
- Legal occupancy
- Recent comparable sales
- Current market competition
For investment properties, additional financial and legal considerations may also be relevant.
2. What is a free property valuation?
An estate agent's market valuation is an estimate of what a property might achieve if offered for sale under prevailing market conditions.
It is not a guaranteed sale price.
It is also different from a formal valuation prepared for mortgage lending, taxation or certain legal purposes.
What happens during a valuation?
An estate agent may:
- Inspect the property.
- Review its condition and accommodation.
- Discuss improvements and relevant documentation.
- Research comparable sales.
- Assess competing listings.
- Identify potential buyer audiences.
- Explain a recommended asking-price strategy.
A useful valuation should be supported by evidence rather than simply presenting the highest possible figure.
3. Valuing an owner-occupied home in Fallowfield
If you own a house that is likely to appeal to owner-occupiers, the valuation will typically focus on comparable residential property evidence.
Relevant factors
These may include:
- Number of bedrooms
- Room proportions
- Condition
- Kitchen and bathroom facilities
- Garden size
- Parking
- Extensions
- Energy performance
- Street location
Why property type matters
A traditional terraced house should generally be compared with similar homes.
A semi-detached house with a driveway and larger garden may require different comparables.
Even within the same postcode, property characteristics can vary.
4. Why recent comparable sales matter
Comparable sales help establish what buyers have actually paid for similar properties.
However, not every nearby sale is a suitable comparison.
What makes a strong comparable?
Consider:
- Similar property type
- Similar floor area
- Similar condition
- Comparable location
- Similar accommodation
- Recent transaction date
Why asking prices are different
A property advertised for £300,000 has not necessarily sold for £300,000.
Current listings can help establish competition, but completed transactions provide a different type of evidence.
An agent should explain how comparable properties support the recommended valuation.
5. How condition affects your home's value
Two houses with the same number of bedrooms can have different values because of their condition.
A recently modernised property may appeal to buyers seeking accommodation that requires little immediate work.
A house needing repairs may attract buyers prepared to undertake improvements.
Important considerations
These include:
- Roofing
- Heating
- Windows
- Electrical condition
- Kitchen and bathrooms
- Damp or ventilation issues
- General decoration
Should you renovate before selling?
Not automatically.
A renovation costing £20,000 does not guarantee an additional £20,000 in sale proceeds.
Before committing to expensive work, seek local valuation advice.
6. How student investment properties are valued
Student rental properties can require a more detailed assessment than a typical owner-occupied home.
In addition to the property's physical characteristics, an investor may examine the income it generates and the costs associated with ownership.
Key considerations
- Current rental income
- Achievable market rent
- Property condition
- Operating expenses
- Tenancy arrangements
- Lawful occupancy
- Licensing
- Compliance
- Comparable investment sales
Why income matters
Rental income helps prospective investors assess the financial performance of a property.
However, the amount of rent received does not automatically establish the property's sale value.
Buyers may also consider financing costs, maintenance, legal restrictions and alternative investments.
7. Understanding gross rental yield
Gross rental yield is a commonly used investment measure.
It compares annual rental income with property value.
Gross yield = annual rental income ÷ property value × 100.
Illustrative example
Imagine a Fallowfield rental property with an estimated value of £300,000 and monthly rent of £1,500.
Annual gross rent would be £18,000.
The gross rental yield would be £18,000 ÷ £300,000 × 100 = 6%.
These figures are hypothetical and are not presented as current Fallowfield market averages.
Why gross yield is only a starting point
Gross yield does not account for expenses such as:
- Maintenance
- Insurance
- Management
- Licensing
- Compliance
- Vacancy
- Service charges
- Mortgage costs
- Tax
An investor should assess the full financial position.
8. What is an HMO?
A house in multiple occupation, commonly called an HMO, generally involves occupants from more than one household sharing certain facilities, subject to statutory definitions and exceptions.
Some student rental properties fall within this category.
Does every HMO need a licence?
Not necessarily under the same licensing scheme.
In England, mandatory HMO licensing generally applies to properties occupied by five or more people forming two or more households who share facilities, subject to the applicable legal criteria.
Additional licensing requirements may apply to other HMOs in designated areas.
Landlords should check current Manchester City Council requirements.
9. How HMO licensing can affect valuation
An HMO's legal and operational position may influence its attractiveness to potential investors.
Relevant questions
- Is the property's current use lawful?
- Is an HMO licence required?
- If licensed, what conditions apply?
- What occupancy is permitted?
- Are relevant safety standards satisfied?
- Are any planning restrictions relevant?
- What are the ongoing compliance costs?
Why documentation matters
Investors may want to review evidence supporting the property's lawful use and operation.
An advertised bedroom count does not necessarily establish the number of occupants legally permitted.
Important distinction
A property should not be marketed as having a particular HMO status or income-generating capacity unless the relevant facts can be substantiated.
10. Comparing a family home with a student investment
Consider two hypothetical terraced houses in Fallowfield.
Property A: Owner-occupied home
A traditional three-bedroom terrace with a garden, family living space and modernised kitchen.
The likely valuation evidence may include recent sales of similar residential houses.
Property B: Student investment
A terraced property used for shared accommodation with documented rental income.
Its assessment may also consider lawful occupancy, tenancy arrangements, rental performance and investor demand.
Which is worth more?
There is no automatic answer.
A student investment is not necessarily more valuable than an owner-occupied house simply because it generates rental income.
The valuation must reflect market evidence and the individual property.
11. Why your exact street matters
Fallowfield contains different residential streets and property characteristics.
Some locations may offer convenient access to local amenities or transport.
Others may differ in traffic, parking, housing style and surrounding land use.
Street-level comparisons
Two similar-looking houses may have different valuations because of:
- Location
- Condition
- Floor area
- Garden size
- Parking
- Layout
- Tenure
- Legal use
A postcode-wide average cannot account for every difference.
12. Tenancy arrangements and selling an investment property
If a property is tenanted, its existing occupancy arrangements may affect the sale.
Selling with tenants
Some buyers may be interested in purchasing an investment subject to existing tenancy arrangements.
Selling with vacant possession
Other buyers may want to occupy the property themselves.
However, selling a property does not automatically terminate a tenancy.
Landlords must follow the law in force and obtain appropriate legal advice about the circumstances.
Why this matters for valuation
The likely buyer audience and lawful availability of the property can affect marketing and sale arrangements.
13. Maintenance and compliance costs for investment properties
Rental properties involve ongoing expenditure.
For HMOs and shared accommodation, requirements can be more complex.
Costs may include:
- Fire safety measures
- Electrical inspections
- Gas safety checks
- Repairs
- Furnishings
- Insurance
- Licensing
- Management
- Communal-area maintenance
These costs can influence investment returns.
A buyer assessing rental income should also consider the expenses necessary to maintain and operate the property lawfully.
14. How should an investor compare Fallowfield properties?
When reviewing potential investments, compare properties using consistent information.
Useful questions
- What is the asking price?
- What is the actual rental income?
- Are the rents sustainable and lawful?
- What are the annual operating costs?
- Is the property appropriately licensed?
- What tenancy arrangements apply?
- What repairs are required?
- Are relevant planning and building matters resolved?
- What comparable investment sales are available?
- What risks could affect future returns?
The answers may be more useful than relying on a headline yield.
15. Can a rental property also appeal to homeowners?
In some circumstances, a property currently used for letting may appeal to owner-occupiers.
However, that depends on its physical layout, legal status, tenancy arrangements and the applicable market.
A shared house is not automatically suitable for immediate occupation as a single family home.
Any proposed change of use or alterations may require professional advice.
Why buyer audience matters
A property's marketing strategy should reflect who can realistically purchase and use it.
This is another reason why a tailored valuation is important.
16. How does presentation affect value?
Whether you are selling a family home or investment property, presentation can influence buyer perceptions.
Owner-occupied homes
Highlight:
- Living space
- Kitchen
- Bedrooms
- Garden
- Architectural character
Investment properties
Present:
- Accommodation accurately
- Communal facilities
- Condition
- Layout
- Relevant lawful occupancy information
Professional photographs and accurate floor plans can help buyers understand the property.
They do not guarantee a particular sale price.
17. Common property valuation mistakes
Relying solely on online estimates
Automated estimates may not fully account for condition, conversions or legal arrangements.
Comparing unlike properties
A licensed HMO should not automatically be compared with a conventional family home.
Assuming rent determines sale price
Rental income is important, but it is not the only factor influencing investment value.
Ignoring maintenance
Outstanding repairs may affect buyer decisions and investment calculations.
Choosing the highest suggested valuation
A higher figure is not necessarily more accurate.
Ask for supporting evidence.
18. What should you prepare for your valuation?
If you own a home or investment property in Fallowfield, gather relevant information before the appointment.
For homeowners
- Property details
- Renovation history
- Extension documentation
- Relevant certificates
- Information about parking and boundaries
For landlords and investors
Also consider:
- Current tenancy documentation
- Rental income records
- Relevant licences
- Safety certificates
- Operating costs
- Maintenance records
- Information about lawful occupancy
Having accurate information available can help the agent assess the property.
19. What questions should you ask your estate agent?
Before deciding to sell, ask:
How did you arrive at this valuation?
Request an explanation of the evidence.
Which comparable sales are most relevant?
Understand why they were selected.
Who is likely to buy the property?
The answer may affect marketing.
Does the current tenancy affect the sale?
Seek appropriate legal advice where necessary.
How should we set the asking price?
Discuss a strategy based on the property and market conditions.
20. Why a free Fallowfield valuation is a useful starting point
A property valuation can help you explore several possible decisions.
You may be considering:
- Selling your family home
- Moving to a larger property
- Downsizing
- Selling an investment
- Releasing equity
- Reviewing a property portfolio
An evidence-led valuation can provide a starting point for further planning.
For financial, mortgage or tax decisions, seek appropriately qualified advice.
21. Your Fallowfield valuation checklist
Before your appointment:
- Identify the property's current use
- Gather details of improvements
- Review relevant comparable sales
- Prepare property documentation
- Check tenure
- Identify maintenance issues
- Gather rental information if applicable
- Confirm relevant licensing details
- Review tenancy arrangements
- Consider your selling objectives
- Prepare questions for the agent
- Book your property valuation
22. Your home and your investment deserve the right valuation
Fallowfield contains a mixture of residential homes and investment properties.
Although two properties may look similar, their value can be influenced by different factors.
For a family home, the focus may be on comparable residential sales, condition and practical living space.
For an investment property, rental performance, legal status and operating costs may also play an important role.
The best starting point is a valuation that reflects your individual property rather than a generic area-wide estimate.
Book your free property valuation in Fallowfield
Thinking about selling your home, student rental or investment property in Fallowfield, Manchester?
At Delisa Miller (NW) Ltd, we help property owners understand their property's position in the local market and explore their selling options.
Whether you own a traditional terrace, family house, buy-to-let property or HMO, contact our team to discuss your next steps.
Book your free, no-obligation property valuation at delisamiller.co.uk/selling/valuation or call 0161 227 0630.
Visit delisamiller.co.uk/locations/fallowfield for our Fallowfield area guide.
Delisa Miller (NW) Ltd — 44 Hulme High Street, Manchester, M15 5JP.
This article provides general property information. It does not constitute a formal RICS valuation, legal advice, financial advice or a verified October 2026 property-price report. Investment values, rental yields and legal obligations should be assessed using current evidence and property-specific information.
Related reading
Got a Property Question?
Our team is here to help. Whether you're buying, selling or letting — get in touch today.