Landlord Advice
Should You Sell or Keep Renting Your Manchester Property in 2026?
A practical guide for Manchester landlords weighing a sale against continued rent — equity, yield, costs, tax and local market factors in 2026.
If you own a property in Manchester, one of the biggest financial decisions you may face in 2026 is whether to sell it or continue renting it out.
Perhaps you purchased your property several years ago and have built up substantial equity. Maybe you're a landlord reviewing your rental income, maintenance costs and changing responsibilities.
Or perhaps you've moved out of your former home and are deciding whether to sell it or retain it as an investment.
Whatever your circumstances, the decision is rarely as straightforward as comparing your property's selling price with its monthly rental income.
Selling could release equity and reduce your ongoing responsibilities. Keeping the property could provide continued rental income and exposure to future changes in property value.
However, both options involve costs, risks and important financial considerations.
For landlords across South Manchester, including Hulme, Fallowfield, Withington, Chorlton, Didsbury, Rusholme, Stretford and Wythenshawe, understanding the full financial picture is essential.
In this guide, Delisa Miller Estate Agents explores the key factors that can help you decide whether selling or continuing to rent your Manchester property is the more suitable option for your circumstances.
1. Should You Sell or Rent Your Manchester Property?
There is no universal answer.
The right decision depends on your financial position, the property itself and what you want to achieve over the coming years.
For some owners, selling may be appropriate because they want to release equity, reduce borrowing or avoid future maintenance costs.
For others, retaining a property may remain consistent with their long-term investment plans.
Reasons you might consider selling
- You want to release equity.
- The property requires substantial repairs.
- Your mortgage or other costs have increased.
- You no longer want landlord responsibilities.
- You want to simplify your finances.
- You plan to use the proceeds for another purpose.
- You are reviewing the balance of your investment portfolio.
Reasons you might consider continuing to rent
- The property generates sustainable rental income.
- You are comfortable with ongoing landlord responsibilities.
- The property remains suitable for letting.
- You do not currently need to release the equity.
- You have sufficient funds for maintenance and unexpected costs.
- Retaining the property fits your long-term financial objectives.
The first step is to understand what your property is worth and how it performs financially.
2. How Much Is Your Manchester Property Worth in 2026?
Before deciding whether to sell, you need an evidence-led estimate of your property's current market value.
Your property may have changed in value since you purchased it.
However, its current value should not be assumed from historical growth or general Manchester house-price headlines.
What affects your property's market value?
Several factors may influence its likely selling price:
Location
A property in Didsbury may attract a different buyer audience from an apartment in Hulme or a student rental in Fallowfield.
Property type
Terraced houses, semi-detached homes, apartments and HMOs can require different valuation approaches.
Condition
A recently renovated home may compare differently with a property requiring significant repairs.
Tenure
Freehold and leasehold properties can involve different obligations and buyer considerations.
Current market evidence
Recent comparable sales, competing listings and buyer interest should inform the valuation.
Why online estimates are not enough
Automated property valuation tools can provide an initial indication.
However, they may not fully account for renovations, maintenance, legal use or individual street characteristics.
A professional valuation can help establish a more realistic starting point.
Considering selling? Book a free Manchester property valuation with Delisa Miller Estate Agents.
delisamiller.co.uk/selling/valuation
3. Understanding Your Property Equity
Equity is the difference between your property's current value and the outstanding borrowing secured against it.
For example, consider the following hypothetical situation.
Estimated property value: £300,000
Outstanding mortgage: £160,000
Estimated gross equity: £140,000
This calculation is:
£300,000 − £160,000 = £140,000
However, this does not mean you would necessarily receive £140,000 after selling.
Costs that may reduce your proceeds
These can include:
- Estate agency fees
- Conveyancing costs
- Mortgage redemption charges
- Early repayment charges where applicable
- Capital Gains Tax where applicable
- Outstanding property-related liabilities
Why equity matters
If a substantial amount of your wealth is tied up in one property, selling may allow you to use some of that capital elsewhere.
However, the financial benefit depends on your individual circumstances and the costs involved.
Before making a decision, calculate your likely net sale proceeds rather than relying solely on the property's estimated value.
4. How Much Rental Income Does Your Property Generate?
For landlords, rental income is an important part of the decision.
However, monthly rent alone does not tell you whether the investment is performing well.
A property generating £1,500 per month may appear attractive, but its financial performance depends on the costs associated with owning and operating it.
Example: Manchester rental property
Consider a hypothetical rental property with:
- Monthly rent: £1,500
- Annual gross rent: £18,000
- Estimated property value: £300,000
The gross rental yield would be:
£18,000 ÷ £300,000 × 100 = 6%
This is an illustrative calculation, not a verified Manchester rental yield.
What is gross rental yield?
Gross rental yield measures annual rental income as a percentage of property value.
It is useful for an initial comparison.
However, it does not account for the costs of operating the property.
Why gross yield can be misleading
Two properties with identical gross yields may produce very different financial outcomes.
One may require extensive maintenance, while another may have lower ongoing expenses.
A meaningful assessment should consider the full financial position.
5. Calculate Your Actual Rental Costs
If you're deciding whether to retain a rental property, review your annual expenses.
Common landlord costs
Mortgage payments
Interest rates and financing arrangements can significantly influence cash flow.
Maintenance and repairs
Boilers, roofing, plumbing, windows and general repairs can create substantial costs.
Insurance
Landlords may require specialist insurance arrangements.
Letting and management fees
Professional management services involve agreed fees.
Compliance
Landlords must meet relevant legal and safety obligations.
Vacant periods
Rental income may stop temporarily between tenancies.
Service charges
Leasehold apartments may involve service charges and contributions towards major building works.
Tax
Rental income and allowable expenses are subject to tax rules that depend on individual circumstances.
Example: Annual operating expenses
Suppose a property generates £18,000 in annual rent.
Illustrative operating expenses might include:
- Maintenance allowance: £1,500
- Insurance: £350
- Management: £1,800
- Compliance and administration: £450
- Vacancy allowance: £900
- Total: £5,000
This would leave £13,000 before mortgage finance costs and tax.
These are hypothetical figures and are not representative of every Manchester property.
The important question
How much income does your property retain after its actual costs?
That figure may be more useful than the headline rent when deciding whether to sell.
6. Could Selling Your Property Be More Beneficial?
Selling may allow you to release capital that is currently tied up in the property.
However, whether doing so is financially advantageous depends on what you would do with the proceeds and the costs of selling.
Questions to consider
- How much equity could you release?
- What would your net sale proceeds be?
- Would selling reduce borrowing?
- Do you need capital for another purchase?
- Could the funds serve another financial objective?
- What taxes might arise?
- What rental income would you give up?
Compare like with like
When evaluating selling against retaining, avoid comparing gross rental income with net sale proceeds.
Instead, consider the expected costs, risks and financial consequences of both options.
A qualified financial adviser or accountant can help with this analysis.
7. Maintenance: Is Your Property Becoming More Expensive to Own?
Property maintenance can be a major consideration for landlords.
Older Manchester properties may require ongoing work to maintain their condition.
This can include:
- Roof repairs
- Heating replacements
- Window maintenance
- Damp investigations
- Electrical work
- Plumbing
- External brickwork
- Drainage
- General refurbishment
Why future maintenance matters
A property that currently generates rental income may require significant expenditure over the next few years.
For example, an ageing boiler or roof may create a future cost that should be included in your financial planning.
Should you sell before major repairs?
Not necessarily.
A property requiring repairs may attract buyers willing to undertake the work, but its condition could influence the sale price.
Alternatively, completing certain repairs may help preserve the property's condition and rental suitability.
The appropriate decision depends on the costs, legal obligations and property-specific market evidence.
8. How Much Time Does Being a Landlord Take?
Owning rental property involves responsibilities beyond collecting rent.
Depending on the tenancy and management arrangements, landlords may need to deal with:
- Maintenance requests
- Contractor appointments
- Tenancy administration
- Rent collection
- Property inspections
- Safety documentation
- Deposit requirements
- Legal compliance
- Tenant communication
- Unexpected problems
Self-management versus professional management
Some landlords prefer to manage their properties personally.
Others appoint an agent to undertake agreed responsibilities.
Professional management may reduce the owner's day-to-day administrative workload.
However, it does not remove all legal responsibilities or guarantee financial returns.
Ask yourself
Do you want to continue managing the property?
Would professional management make ownership more practical?
Or would selling better suit your current circumstances?
These are legitimate considerations alongside rental income.
9. Understanding Manchester's Different Rental Markets
Manchester is not one uniform property market.
Rental characteristics can vary by neighbourhood, property type and tenancy arrangements.
Fallowfield
Fallowfield includes traditional residential properties and accommodation associated with the student rental market.
Landlords may need to consider shared housing, tenancy cycles and HMO requirements where relevant.
Withington
Withington contains period houses, flats and a mixture of residential rental properties.
Condition, layout and intended use can influence letting and resale considerations.
Rusholme
Rusholme contains traditional terraced housing and shared accommodation.
Property owners should assess rental arrangements, maintenance and lawful occupancy.
Hulme
Hulme includes apartments and other residential properties.
For leasehold landlords, service charges, lease restrictions and building management can be important.
Didsbury and Chorlton
These neighbourhoods contain a mixture of period houses, apartments and other residential accommodation.
A property's exact characteristics should guide its rental and resale assessment.
Why local knowledge matters
A landlord should not assume that demand, rent or property values are identical across South Manchester.
Current comparable evidence is essential.
10. Should You Sell a Tenanted Property?
Selling a rental property while tenants are living there is possible.
However, existing tenancy arrangements can influence the sale.
Selling to another investor
Some investors may consider purchasing a property subject to an existing tenancy.
Relevant information can include rental income, tenancy terms, property condition and compliance.
Selling to an owner-occupier
Other buyers may wish to occupy the property themselves.
This can create different requirements concerning possession and completion.
Important legal consideration
Selling a property does not automatically end a tenancy.
Landlords must follow the law applicable to the tenancy and should obtain appropriate legal advice before making plans that depend on vacant possession.
How can this affect value?
The likely buyer audience, tenancy arrangements and property's legal position may affect the marketing strategy.
A valuation should reflect these circumstances.
11. How Do Mortgage Costs Affect Your Decision?
Mortgage arrangements can materially influence whether retaining a property is financially sustainable.
Consider:
- Current interest rate
- Mortgage balance
- Repayment structure
- Remaining fixed-rate period
- Potential refinancing costs
- Early repayment charges
- Affordability under different scenarios
Why this matters
A property may generate a positive cash flow under one financing arrangement but perform differently if borrowing costs change.
Mortgage advice should be obtained from an appropriately qualified professional.
12. What About Capital Gains Tax?
Selling a property may create a Capital Gains Tax liability.
The position depends on factors such as:
- Purchase price
- Selling price
- Allowable costs
- Ownership structure
- Previous occupation
- Reliefs and exemptions
- Current tax rules
Former main residences
If the property was previously your main home, the tax position may differ from that of a property purchased solely as an investment.
Why seek professional advice?
Capital Gains Tax calculations can be complex.
Do not assume that the difference between your purchase price and sale price is the amount on which tax will necessarily be calculated.
Consult a qualified accountant or tax adviser before deciding to sell.
13. What About Future Property Prices?
Some landlords retain property because they hope its value will increase over time.
Others sell because they prefer to release capital now.
Can Manchester property prices rise?
Property values can increase or decrease.
Future performance depends on factors including:
- Mortgage affordability
- Economic conditions
- Housing supply
- Buyer demand
- Property condition
- Local circumstances
Is future growth guaranteed?
No.
Past price growth does not guarantee future results.
A decision to retain a property should not rely solely on an assumption that its value will increase.
14. Could You Release Equity Without Selling?
Some property owners consider refinancing as an alternative to selling.
This may provide access to capital while retaining ownership.
However, it can also increase borrowing, financing costs and financial risk.
Questions to ask
- How much additional borrowing is available?
- What would the repayments be?
- Could rental income support the costs?
- What fees apply?
- What happens if rates or circumstances change?
Equity release through borrowing is not automatically preferable to selling.
Seek regulated mortgage or financial advice before proceeding.
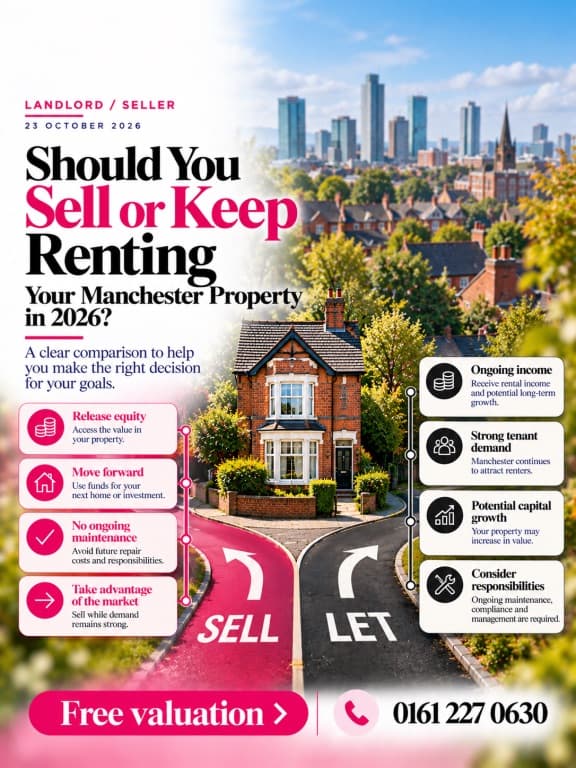
15. Selling Versus Renting: A Practical Comparison
Equity
- Sell the property: Potentially release capital after costs.
- Continue renting: Equity remains invested in the property.
Rental income
- Sell the property: Rental income ends.
- Continue renting: Potential ongoing income.
Maintenance
- Sell the property: Future ownership responsibilities generally end after completion.
- Continue renting: Ongoing maintenance responsibilities.
Management
- Sell the property: No ongoing landlord management after sale.
- Continue renting: Management continues directly or through an agent.
Property value changes
- Sell the property: No further direct exposure after sale.
- Continue renting: Exposure to future rises or falls.
Tax
- Sell the property: Potential disposal-related tax.
- Continue renting: Rental income and eventual disposal may have tax consequences.
Flexibility
- Sell the property: Capital may be available for other purposes.
- Continue renting: Property remains an owned asset.
Neither option is universally better.
The decision should reflect your circumstances and financial objectives.
16. Five Questions Every Manchester Landlord Should Ask
Before deciding whether to sell or retain a rental property, consider these five questions.
Question 1: What is my property worth today?
Obtain a realistic valuation supported by comparable evidence.
Question 2: How much net income does it generate?
Review rental income after operating costs, with finance and tax considered separately.
Question 3: What expenditure is likely over the next few years?
Assess maintenance, compliance and possible major works.
Question 4: Do I want to remain a landlord?
Consider the time, responsibility and administration involved.
Question 5: What are my longer-term financial plans?
Think about how the property fits your wider financial position.
17. When Selling May Be Worth Considering
Selling may be appropriate to investigate when:
- You want to release equity.
- Rental income is insufficient for your objectives.
- The property requires substantial expenditure.
- You want to reduce management responsibilities.
- You are restructuring your investments.
- You have another use for the capital.
- Retaining the property no longer fits your plans.
These factors do not automatically mean you should sell.
They indicate that reviewing your options may be useful.
18. When Keeping Your Rental Property May Be Worth Considering
Retaining a property may be appropriate to investigate when:
- Rental income remains financially sustainable.
- You can meet maintenance and compliance costs.
- You are comfortable with landlord responsibilities.
- You have sufficient financial reserves.
- You do not need to release the equity.
- The property fits your long-term investment objectives.
Again, the decision depends on individual circumstances.
19. How Can a Property Valuation Help?
An accurate market valuation provides information that can support your decision.
It can help you estimate:
- Current property value
- Potential gross equity
- Likely sale proceeds before relevant costs
- An appropriate asking-price strategy
- Potential buyer audiences
- How the property compares with recent sales
Why local comparable evidence matters
An apartment in Hulme, a student rental in Fallowfield and a family house in Wythenshawe may attract different buyers.
Their valuations should reflect the individual property and relevant comparable sales.
Free Manchester property valuation
If you're considering selling, Delisa Miller Estate Agents can discuss your property and the next steps involved in obtaining a market valuation.
Book your free valuation:
delisamiller.co.uk/selling/valuation
20. How to Prepare if You Decide to Sell
If you decide to market your Manchester property, preparation can help the process run more smoothly.
Step 1: Obtain a valuation
Understand the property's likely market position.
Step 2: Review tenancy arrangements
If the property is rented, seek advice on the legal and practical implications.
Step 3: Gather documents
These may include:
- Title information
- Relevant tenancy documentation
- Safety certificates
- Planning and building records
- Leasehold information where applicable
- Relevant guarantees
Step 4: Assess maintenance
Identify repairs and discuss which matters should be addressed before marketing.
Step 5: Prepare photographs and floor plans
Accurate marketing materials help buyers understand the accommodation.
Step 6: Agree on a marketing strategy
Discuss asking price, buyer audience and viewing arrangements.
21. How to Prepare if You Decide to Keep Renting
If retaining the property remains your preferred option, review its financial and operational position.
Financial review
- Current rental income
- Operating expenses
- Mortgage costs
- Maintenance reserves
- Vacancy allowance
- Tax considerations
Property review
- General condition
- Safety obligations
- Licensing where relevant
- Upcoming repairs
- Tenancy arrangements
Management review
- Time spent managing the property
- Communication and maintenance workload
- Costs of professional management
- Record-keeping and compliance
An organised review can help identify areas that require attention.
22. Common Mistakes When Deciding Whether to Sell or Rent
Mistake 1: Looking only at monthly rent
Gross rent does not represent net financial performance.
Mistake 2: Assuming the property has increased in value
Use current comparable evidence.
Mistake 3: Ignoring future maintenance
Major repairs can affect financial outcomes.
Mistake 4: Forgetting selling costs and taxes
Calculate likely net proceeds.
Mistake 5: Assuming tenants can be asked to leave immediately
Tenancy rights and possession procedures must be respected.
Mistake 6: Relying on predicted property-price growth
Future market performance is uncertain.
Mistake 7: Ignoring personal circumstances
A financially viable investment may still be unsuitable if your priorities have changed.
23. Your Manchester Landlord Decision Checklist
Before making your final decision:
- Obtain a current property valuation.
- Confirm your mortgage balance.
- Calculate estimated equity.
- Review annual rental income.
- Calculate operating expenses.
- Assess financing costs.
- Review maintenance requirements.
- Check compliance obligations.
- Review tenancy arrangements.
- Consider management workload.
- Estimate selling costs.
- Obtain appropriate tax advice.
- Consider future financial needs.
- Assess your long-term objectives.
- Discuss your options with relevant professionals.
24. Frequently Asked Questions
Is it better to sell or rent out my Manchester property in 2026?
It depends on your property's market value, rental income, operating costs, financing, tax position and long-term objectives. Neither option is automatically better.
Can I sell my Manchester property with tenants living in it?
Yes, a property can be sold subject to existing tenancy arrangements. However, the tenancy affects the legal and practical arrangements, and selling does not automatically terminate it.
How do I know what my Manchester rental property is worth?
An estate agent can assess the property using relevant comparable sales, condition, location, tenure and other characteristics. Investment-related factors may also be relevant.
Is rental yield the same as profit?
No. Gross rental yield compares annual rent with property value. It does not deduct expenses, finance costs or tax.
Should I sell if my rental property needs repairs?
Not necessarily. Compare the likely repair costs, property value, financial performance and your objectives before deciding.
Can I release equity without selling?
Potentially, through refinancing or other borrowing arrangements, subject to eligibility. This can increase debt and costs, so regulated advice is important.
Do I have to pay Capital Gains Tax when selling a rental property?
A taxable gain may arise, depending on your circumstances and the relevant rules. Obtain professional tax advice.
Can Delisa Miller value my property if I'm not ready to sell?
You can contact Delisa Miller Estate Agents to discuss a free, no-obligation market valuation, even if you're still exploring your options.
25. The Final Decision: Sell or Keep Renting?
For Manchester property owners, the decision to sell or retain a rental property should be based on more than a single number.
Your property value matters.
Your rental income matters.
But so do maintenance costs, financing, legal responsibilities, tax implications and your personal plans.
Selling may release capital and bring your landlord responsibilities to an end. Continuing to rent may provide ongoing income while allowing you to retain ownership.
The most appropriate option depends on your individual circumstances.
Before making a decision, establish what your property could realistically sell for and review the full financial implications of both choices.
Find Out What Your Manchester Property Could Be Worth
Are you a landlord or homeowner considering whether to sell your Manchester property in 2026?
At Delisa Miller Estate Agents, we help property owners across South Manchester explore their selling options.
Whether you own an apartment in Hulme, a student investment in Fallowfield, a period terrace in Withington or a family home elsewhere in Manchester, understanding your property's market value is a useful first step.
Book your FREE, no-obligation property valuation today.
Website: delisamiller.co.uk/selling/valuation
Telephone: 0161 227 0630
Delisa Miller (NW) Ltd — 44 Hulme High Street, Manchester, M15 5JP.
Disclaimer: This article provides general property information and does not constitute financial, mortgage, tax, investment or legal advice. The financial examples are illustrative, not verified October 2026 market data. Property owners should seek advice from appropriately qualified professionals and verify current legislation before making decisions.
Related reading
Find out what your Manchester property could be worth
Book a free, no-obligation market valuation with Delisa Miller Estate Agents.